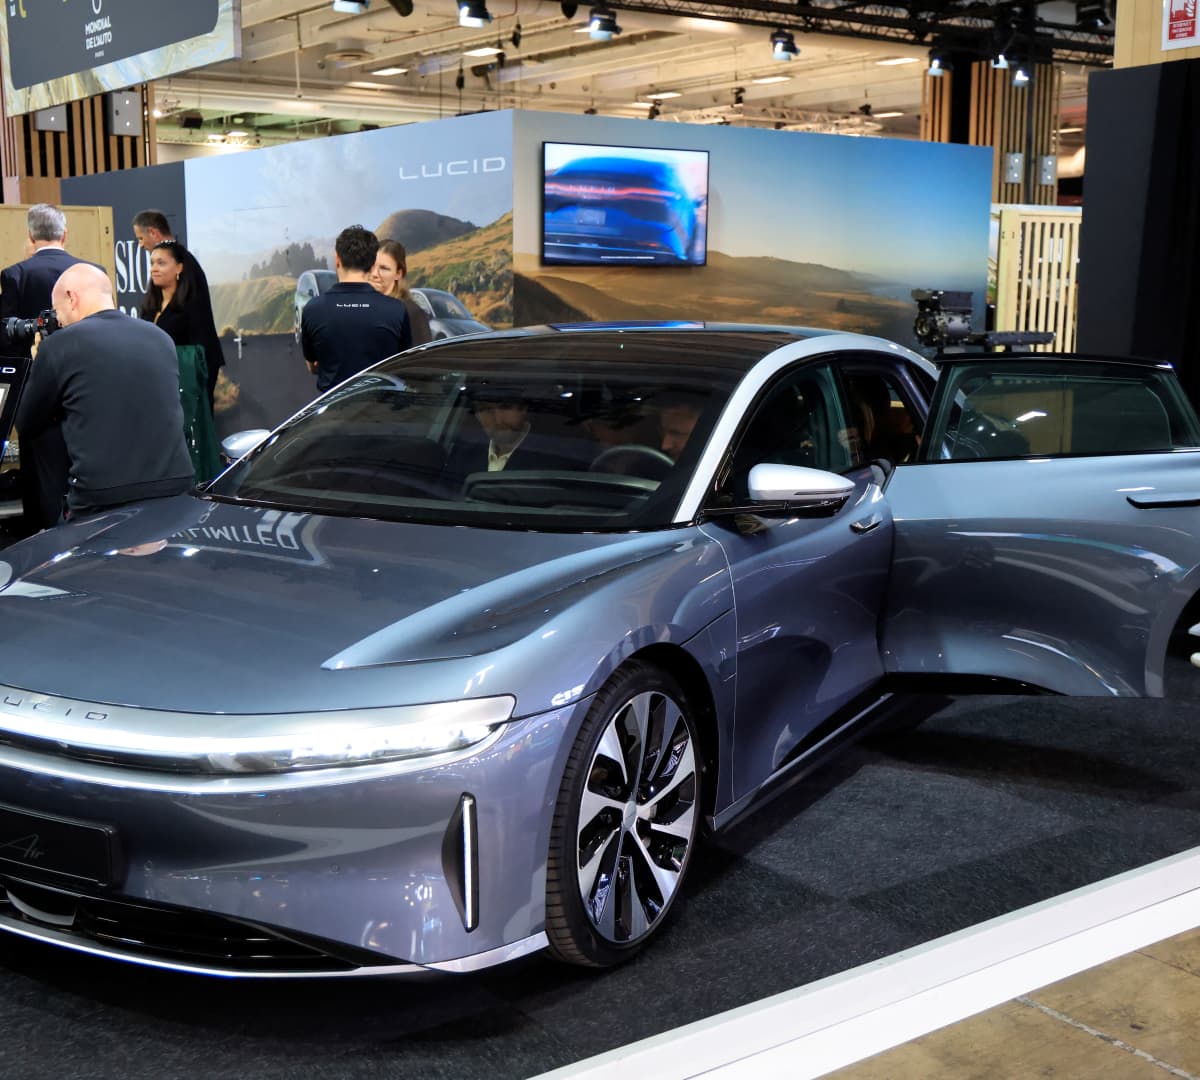
Lucid Group missed Wall Street's third-quarter expectations, and the company is still running an "operational reset" aimed at cutting costs and narrowing losses. Those are the facts on the table. The question is whether the company is building toward something durable or simply surviving on the largesse of its largest shareholder.
The company's own numbers make the case for caution. Lucid reported third-quarter revenue of $336.6 million and a loss of $3.31 per share. Its net loss for the quarter was $830.9 million, which is smaller than the $978.4 million loss a year earlier. The adjusted EBITDA loss of $717.7 million did beat the average Wall Street estimate of a $611 million loss. That is progress on paper, but it is progress measured against a company that was bleeding badly. A narrower loss is not the same as a business that makes money.
The $1.75 billion increase in a delayed draw term loan from Saudi Arabia's Public Investment Fund is the most consequential detail in the report. The fund is already the company's largest shareholder, and the additional capital lifts total liquidity to $3.75 billion, up from $2 billion at the end of the third quarter. Lucid says this will help fund operations and key investments into the fourth quarter of 2027. That is useful breathing room. It also means that the company's runway depends heavily on a single anchor investor. Investors should ask what that dependence means for strategic independence, and they should press management for a clearer picture of when the business can fund itself.
CEO Silvio Napoli, who began leading the company in June, has announced cost-cutting, a delay of the midsize vehicle to the second half of next year, and $1.4 billion in cash flow improvements this year. Those are sensible steps. But the turnaround also rests on a robotaxi program with Uber and Nuro, a factory under construction in Saudi Arabia, and a vehicle that has now been pushed back. Each of those bets carries its own timeline risk. Management has promised a midterm plan and targets early next year, and that is where the real test lies.
Lucid's stock fell roughly 5% in aftermarket trading, a reaction that reflects a market still unconvinced. My view is simple. The company should publish its midterm targets as early as possible, with specific milestones on cash burn and production, and it should report against them every quarter. Until it does, the Saudi capital should be read as a bridge rather than a verdict that the business is sound.